

Question 76
For a loan portfolio, unexpected losses are charged against:
Question 77
Which of the following is not a tool available to financial institutions for managing credit risk:
Question 78
Which of the following statements is true:
I. Confidence levels for economic capital calculations are driven by desired credit ratings II. Loss distributions for operational risk are affected more by theseverity distribution than the frequency distribution III. The Advanced Measurement Approach (AMA) referred to in the Basel II standard is a type of a Loss Distribution Approach (LDA) IV. The loss distribution for operational risk under the LDA (Loss Distribution Approach) is estimated by separately estimating the frequency and severity distributions.
I. Confidence levels for economic capital calculations are driven by desired credit ratings II. Loss distributions for operational risk are affected more by theseverity distribution than the frequency distribution III. The Advanced Measurement Approach (AMA) referred to in the Basel II standard is a type of a Loss Distribution Approach (LDA) IV. The loss distribution for operational risk under the LDA (Loss Distribution Approach) is estimated by separately estimating the frequency and severity distributions.
Question 79
When fitting a distribution in excess of a threshold as part of the body-tail distribution method described by the equation below, how is the parameter 'p' calculated.
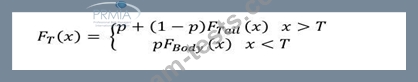
Here, F(x) is the severity distribution. F(Tail) and F(Body) are the parametric distributions selected for the tail and the body, and T is the threshold in excess of which the tail is considered to begin.
Here, F(x) is the severity distribution. F(Tail) and F(Body) are the parametric distributions selected for the tail and the body, and T is the threshold in excess of which the tail is considered to begin.