

Question 11
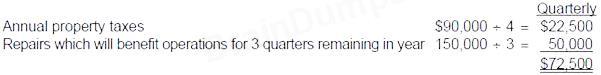
On March 15, 1992, Krol Co. paid property taxes of $90,000 on its office building for the calendar year
1 992. On April 1, 1992, Krol paid $150,000 for unanticipated repairs to its office equipment. The repairs
will benefit operations for the remainder of 1992. What is the total amount of these expenses that Krol
should include in its quarterly income statement for the three months ended June 30, 1992?
Question 12
Reclassification adjustments must be shown in the financial statement that discloses comprehensive
income:
income:
Question 13
On January 2, 1993, Quo, Inc. hired Reed to be its controller. During the year, Reed, working closely with
Quo's president and outside accountants, made changes in accounting policies, corrected several errors
dating from 1992 and before, and instituted new accounting policies.
Quo's 1993 financial statements will be presented in comparative form with its 1992 financial statements.
This question represents one of Quo's transactions. List B represents the general accounting treatment
required for these transactions. These treatments are:
. Cumulative effect approach - Include the cumulative effect of the adjustment resulting from the
accounting change or error correction in the 1993 financial statements, and do not restate the 1992
financial statements.
. Retroactive or retrospective restatement approach - Restate the 1992 financial statements and adjust
1 992 beginning retained earnings if the error or change affects a period prior to 1992.
. Prospective approach - Report 1993 and future financial statements on the new basis but do not restate
1 992 financial statements.
During 1993, Quo increased its investment in Worth, Inc. from a 10% interest, purchased in 1992, to 30%,
and acquired a seat on Worth's board of directors. As a result of its increased investment, Quo changed
its method of accounting for investment in Worth, Inc. from the cost method to the equity method.
List B
Question 14
During a period when an enterprise is under the direction of a particular management, its financial
statements will directly provide information about:
statements will directly provide information about:
Question 15
On January 2, 1993, Quo, Inc. hired Reed to be its controller. During the year, Reed, working closely with
Quo's president and outside accountants, made changes in accounting policies, corrected several errors
dating from 1992 and before, and instituted new accounting policies.
Quo's 1993 financial statements will be presented in comparative form with its 1992 financial statements.
This question represents one of Quo's transactions. List A represents possible clarifications of these
transactions as: a change in accounting principle, a change in accounting estimate, a correction of an
error in previously presented financial statements, or neither an accounting change nor an accounting error.
Item to Be Answered
Quo manufactures heavy equipment to customer specifications on a contract basis. On the basis that it is
preferable, accounting for these long-term contracts was switched from the completed-contract method to
the percentage-of-completion method.
List A (Select one)