

Question 16
Adam Corp. had the following infrequent transactions during 1989:
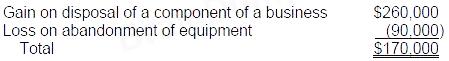
. A $190,000 gain on reacquisition and retirement of bonds. This material event is also considered
unusual for Adam Corp.
. A $260,000 gain on the disposal of a component of a business. Adam continues similar operations at
another location.
. A $90,000 loss on the abandonment of equipment.
In its 1989 income statement, what amount should Adam report as total infrequent net gains that are not
considered extraordinary?
Question 17
Coffey Corp.'s trial balance of Income Statement Accounts for the year ended December 31, 1988 as
follows: Coffey's income tax rate is 30%. The gain on debt extinguishment is considered a usual and
recurring part of Coffey's operations. Coffey prepares a multiple-step income statement for 1988.

Income from operations before income tax is:
follows: Coffey's income tax rate is 30%. The gain on debt extinguishment is considered a usual and
recurring part of Coffey's operations. Coffey prepares a multiple-step income statement for 1988.
Income from operations before income tax is:
Question 18
Which of the following statements regarding fair value is/are correct?
I. The fair value of an asset or liability is specific to the entity making the fair value measurement.
II. Fair value is the price to acquire an asset or assume a liability.
III. Fair value includes transportation costs, but not transaction costs.
IV. The price in the principal market for an asset or liability will be the fair value measurement.
Question 19
A material loss should be presented separately as a component of income from continuing operations
when it is:
when it is:
Question 20
There are multiple active markets for a financial asset with different observable market prices:
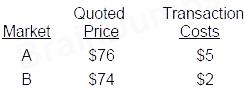
There is no principal market for the financial asset. What is the fair value of the asset?
There is no principal market for the financial asset. What is the fair value of the asset?